What is equipment leasing, and why can it be better than a loan or outright purchase?
Leasing is straightforward: use the asset immediately, pay gradually and take ownership at the end. However, leasing companies often present complex formulas and online calculators that can confuse inexperienced customers.
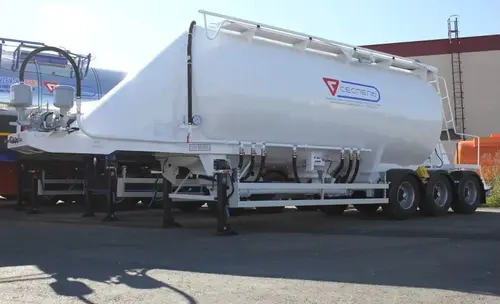
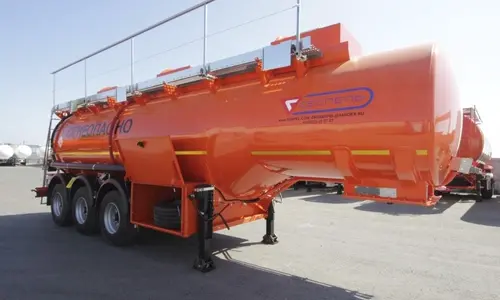
Sespel Finance specialists have prepared a short guide answering common leasing questions. Using the company’s semi-trailer leases as an example, we explain simply how leasing works and why it can benefit even small businesses.
How does leasing differ from a loan?
A loan is money provided by a bank. The bank assesses your ability to pay, then you repay the debt gradually with interest. Large loans may require collateral. Leasing works differently and resembles renting: it does not require collateral or a perfect credit history.
You ask a leasing company to buy equipment, such as a car, truck or semi-trailer, and pay for it in instalments. First comes an advance, for example 30% of the price, followed by equal monthly payments throughout the lease.
At the end, you can buy the equipment from the leasing company and take ownership. The final buyout payment is usually nominal, for example RUB 1,000. The contract and schedule are arranged so that monthly payments cover most of the equipment’s value.
Over the lease term, you pay:- An upfront advance: for example, from 30% of the semi-trailer price at Sespel Finance
- The remaining equipment cost in equal instalments: for example, 70% over three years, or 36 payments
- A usually nominal buyout payment, such as RUB 1,000
You can therefore use leased equipment from day one without paying the full price immediately, and keep it once payment is complete.
How does the leasing company earn money?
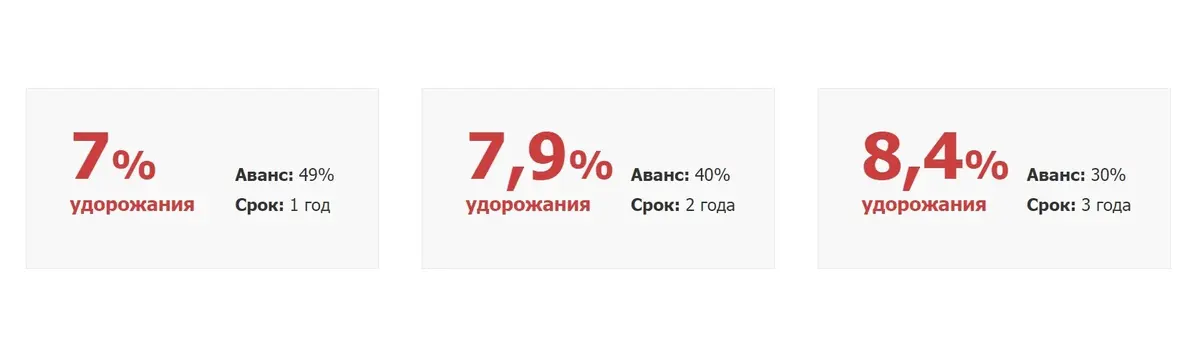
You pay slightly more overall than for an outright purchase in return for spreading the cost. For example, a three-year Sespel Finance semi-trailer lease with a 30% advance involves a total additional cost of 8.4%. Other programmes are also available:
Why can leasing benefit even a small business?
Leasing avoids withdrawing the full equipment cost from working capital at once. A leased semi-trailer or tanker can begin fulfilling orders and generating revenue from day one. If it earns more than the monthly lease payment, you come out ahead.
Leasing companies insure equipment in volume and can secure favourable insurance rates. At Sespel Finance, comprehensive vehicle insurance is already included in lease payments on better terms than retail policies, with no additional insurance outlay required.
Leasing can also be more economical than a loan because of tax savings. Lease costs count as direct expenses, reducing taxable profit. VAT on lease payments can be deducted, meaning the state refunds part of the VAT.
Is equipment leasing as slow and costly to arrange as a loan?
Sespel Finance reviews applications within 24 hours. You need your tax identification number (INN) and just three documents:- A trial balance for selected accounts
- A balance sheet and income statement for the previous year and the latest reporting date
- A short application form that Sespel Finance staff will help complete
Originals are not required: scan the documents and email them to Sespel Finance.